Is Customer Data Becoming More Valuable Than Rent?
Is Customer Data Becoming More Valuable Than Rent?
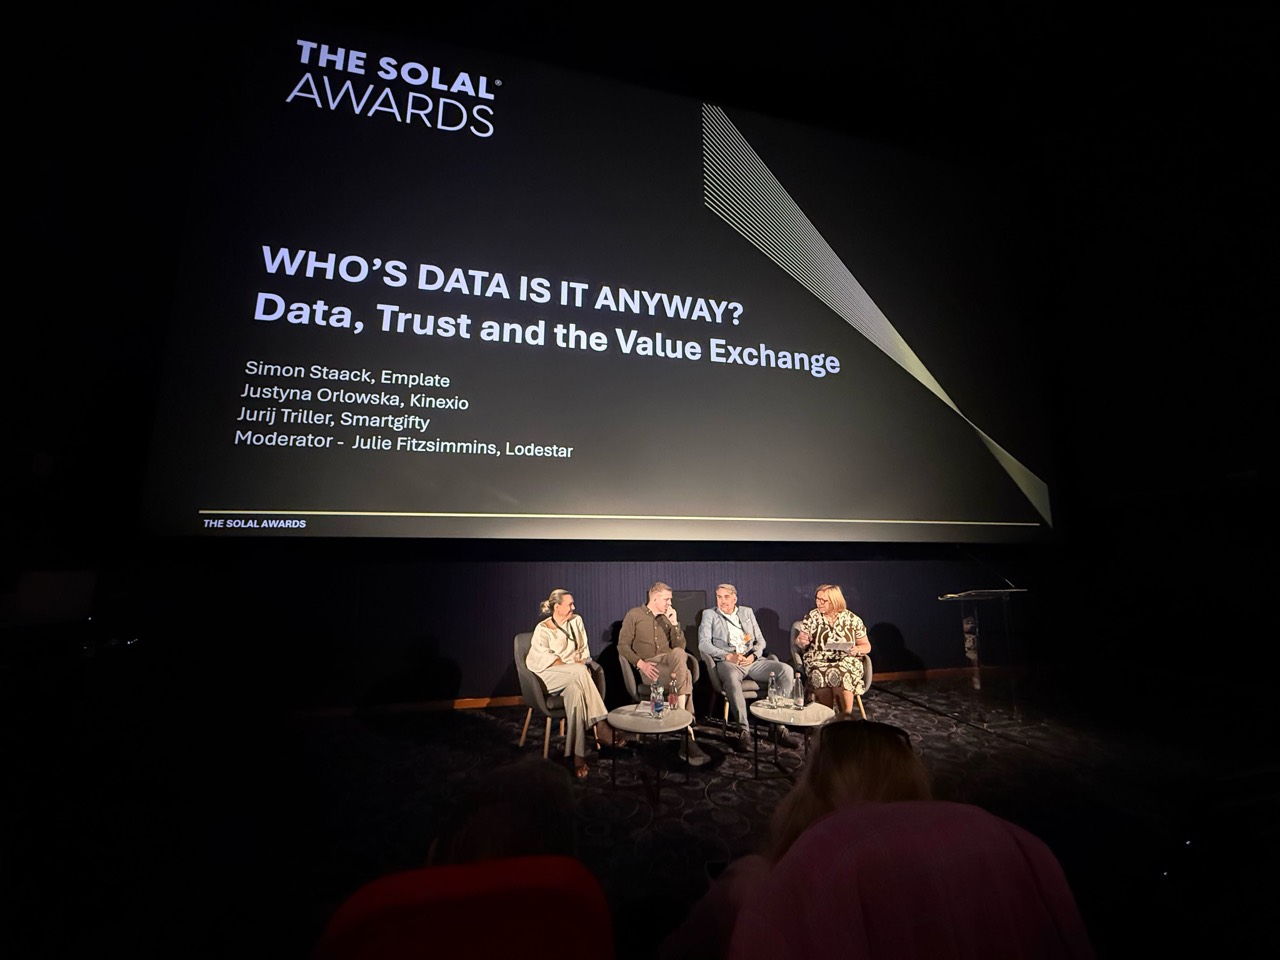
Jurij Triller (SOS) shares his perspective from that discussion, exploring data ownership, AI personalisation, retailer collaboration and what truly underpins destination value.
Customer Ownership & Data Governance
When a customer shops in a centre, spends with a retailer, and parks using an app, who really owns that customer relationship?
In reality, the customer relationship is shared across multiple parties:
- The retailer understands what the customer buys;
- The parking app operator knows when they arrive and leave;
- The shopping centre oversees the broader visitor journey and dwell experience.
The key is not fighting over who "owns" the customer, but connecting these individual touchpoints to deliver the greatest value back to the visitor. A shopping centre can build an authentic, direct relationship through shared loyalty schemes, unified gift cards, tailored events, and integrated services that link its various businesses together.
Should landlords have equal access to customer data generated by retailers operating in their centres?
Yes, but strictly to the data that helps improve the performance and operation of the centre as a whole. This does not automatically mean blanket access to every retailer’s proprietary records. Retailers invest heavily in their direct customer relationships, and it is completely understandable that they want to protect them.
However, when smaller independent tenants lack the budget and expertise to build complex loyalty systems, the shopping centre is the one stepping in to make that investment.
The ideal model is strategic collaboration: retailers share aggregated insights on sales trends and campaign responses, while the landlord contributes macro intelligence on overall footfall patterns, catchment dynamics, and the impact of cross-centre activations. For most operational decisions, aggregated data that safeguards individual identities is more than sufficient. When both sides co-generate data through shared gift card or loyalty programmes with pre-agreed ground rules, sharing succeeds because it produces tangible sales uplift.
Is the industry’s biggest challenge that shopping centre owners still know less about their customers than Google, Apple, and Meta?
While that knowledge gap exists, our biggest immediate challenge is how poorly shopping centres utilise the data they already possess. Most centres currently capture footfall curves, parking durations, gift card redemptions, and loyalty interactions, but these streams sit in disconnected silos.
A centre does not need to emulate Big Tech by tracking every facet of an individual’s digital life. It simply needs to know why visitors come, what friction they encounter, what brings them back, and how to convert their presence into sales for tenants. Google, Apple, and Meta dominate digital intent, but shopping centres own the tangible physical experience. The real commercial opportunity lies in bridging that physical interaction with actionable insights.
Business Value & Asset Valuation
If customer data creates measurable sales uplift, should landlords be monetising data in the same way they monetise footfall?
Yes, but they should monetise the commercial value created, not the raw data itself. If a centre demonstrably boosts a retailer's revenue through intelligent profiling and targeted campaigns, it is entirely fair that this contribution is rewarded.
This can take the form of sponsored joint campaigns, bespoke tenant analytics, or agreed turnover-linked incentives. Crucially, the centre must be able to isolate true incremental sales—distinguishing purchases that would have happened anyway from the uplift directly spurred by the campaign. Footfall merely shows who walked past the door; data reveals what prompted them to buy and what will encourage them to return.
Could customer data eventually become more valuable than rental income?
Absolutely, provided it is deployed intelligently. Data sitting idle on a server has no monetary value; its value is realised only when it drives store turnover, dwell time, and tenant retention.
As data enables more relevant customer propositions and higher tenant sales, it naturally strengthens rent-paying capacity and overall property value. Across an entire portfolio of centres, shared data infrastructure and cross-asset consumer services could evolve into substantial auxiliary business lines. One might even ask: why not offer tenants rent incentives in direct exchange for structured data sharing? Ultimately, the decisive question for any asset is: how much more are our physical square metres worth because we understand our visitors better?
Is the next generation of shopping centre valuations going to be driven by data assets as much as physical assets?
Data will play an increasingly prominent role in valuations, though physical location, architecture, and net operating income will remain primary. Its weight in any valuation will hinge entirely on whether the landlord can prove that data directly supports asset profitability.
A massive customer database does not warrant a higher yield on its own. It matters only if it protects occupancy, improves tenant mix, and drives footfall frequency. If two properties have identical square footage and tenant profiles, the one armed with actionable customer intelligence has far greater predictability of future cash flows.
Landlord-Tenant Relationships
Are retailers willing to share customer data, or are they protecting their last source of competitive advantage?
Both. And we have to respect their hesitation. Brands have spent decades building proprietary customer equity; they will not risk leaking hard-won customer relationships to competitors or landlords without clear safeguards.
Retailers open up when the value exchange is unmistakable: lower customer acquisition costs, higher basket sizes, and transparent sales impact. Aggregated performance metrics are often the best starting point to prove goodwill. Centres often falter because they demand data without explaining the return for the tenant. Trust is everything: clear boundaries, guaranteed confidentiality, and demonstrable revenue growth make retailers willing partners.
Which creates more value for occupiers: lower rent or better customer insights?
Lower rent provides immediate, short-term margin relief. Better customer insights, however, compound into greater long-term profitability—provided the retailer possesses the operational agility to act on them.
If actionable data allows an occupier to refine their merchandise mix, eliminate dead stock, and run sharper promotions, the resulting profit can easily outpace baseline rent savings. If I were an occupier, I would weigh rent reductions against the measurable incremental net margin generated through landlord-supported customer insights.
If a centre can demonstrably drive sales through data-led marketing, should leases evolve to reflect that value creation?
Yes. Commercial lease structures should evolve alongside shared value creation. However, a top-line sales increase alone does not automatically justify higher fixed rent; leases must account for tenant profitability, shared marketing costs, and attribution.
Pre-agreed joint marketing mechanisms or performance-tied frameworks can align both parties around a common goal: investing collaboratively in activations that measurably enrich the customer journey and expand store margins.
Artificial Intelligence & Personalisation
Will AI make the traditional shopping centre marketing team obsolete within five years?
No, but their day-to-day focus will undergo a fundamental transformation. AI will automate repetitive tasks—asset generation, multivariate testing, operational reporting, and audience segmentation.
However, machines cannot replicate local community empathy, tenant negotiation, sensory physical event design, or nuanced brand curation. Marketers will spend less time drafting copy and far more time understanding customer psychology, steering high-level brand strategy, and auditing algorithmic recommendations.
How comfortable should consumers be with centres using AI to predict where they shop, eat, and spend?
It is acceptable as long as the shopper understands how their data is being applied, retains explicit control, and receives unmistakable utility in return.
Consider modern tourist destinations: visitors welcome intuitive recommendations for quality dining or local culture because it enhances their trip. But if a visitor feels constantly surveilled, or senses an algorithm exploiting behavioral weaknesses to induce impulse spending, trust collapses. High-quality personalisation feels like an attentive, frictionless concierge service, never an intrusive trap.
Are we heading towards a future where every shopper receives a different version of the same shopping centre?
Yes, precisely as forward-thinking tourism destinations are doing today. While the physical building and social atmosphere remain shared, the digital overlay—perks, dining recommendations, and event invites—will be uniquely customised.
A family visiting on a Saturday might receive notices about children's workshops and casual dining spaces, while an office worker popping in at noon receives seamless mobile ordering for a quick lunch. The goal is to make navigation effortless without stifling serendipity and spontaneous discovery.
„A large customer database does not, in itself, mean a higher valuation. What matters is whether the data helps increase tenants' sales, maintain occupancy, and encourage repeat visits."
Consumer Trust & Transparency
If shoppers were told exactly how much data is collected about their visits, would they be comfortable with it?
It depends on transparency and utility. Shoppers readily accept data capture when the return is tangible—such as frictionless automated parking or tailored rewards—and when retention limits are clear.
They push back when tracking happens covertly or for obscure backend profiling. The best litmus test for any asset manager is simple: Can we explain our data collection to our visitors plainly, face-to-face, without hesitation or embarrassment? If the answer is no, the strategy needs an immediate rethink.
Would customers trade more personal data in exchange for free parking, rewards, or exclusive experiences?
Yes, millions already do every day, provided the exchange is fair and proportionate. A shopper may happily exchange basic trip details for complimentary parking, yet balk at handing over their full household financial footprint. Fair exchange requires modular choices: let visitors opt in to basic convenience without forcing them into exhaustive profiling.
Are we just one scandal away from customers refusing to share data entirely?
A major breach or breach of trust will not halt digital interaction permanently, but it creates profound skepticism. If visitors discover that their habits were quietly commodified or passed to third parties without consent, they disengage immediately. Trust is built brick by brick through daily privacy compliance, robust data governance, and open dialogue.
The Future of Retail Destinations
Can a shopping centre become truly customer-centric without owning and integrating customer data?
An asset can be customer-friendly through courteous staff and clean facilities, but it cannot be systematically customer-centric without unified data.
Treating parking, events, loyalty apps, and tenant transactions as isolated islands blinds management to the holistic customer journey. By connecting those dots, centres uncover operational bottlenecks and identify real customer needs. Crucially, you do not need invasive personal identities to achieve this; clean, aggregated behavioral insights are more than enough.
Are shopping centres evolving into retail destinations, entertainment destinations, or data businesses?
They must converge into all three. Retail provides convenience and discovery; leisure, food, and culture provide community and dwell time; data provides the connective tissue that aligns operations with evolving consumer habits. Management will be guided by data, but the ultimate product being sold will always be the visceral experience of a vibrant physical environment.
What will matter most in ten years: location, experience, or information?
If forced to choose, experience remains supreme.
Location dictates physical access and baseline footfall. Information refines operations and tenant curation. But experience is the sole reason human beings choose to return. Experience encompasses seamless parking, intuitive layout, friendly human service, and a welcoming environment. Location makes a visit possible; information makes it relevant; experience makes it memorable.
Challenging Realities
What customer data would you ban your organisation from collecting?
I would forbid collecting any data point for which the organisation lacks a transparent operational purpose. Specifically, any speculative profiling regarding personal health, religious or political beliefs, or financial distress must be strictly off-limits. We exist to make shopping and social visits enjoyable, not to exploit consumer vulnerabilities.
What dataset would your organisation like to have that it currently cannot access?
The holy grail remains a unified, privacy-compliant map showing how visitor footfall directly converts into transactions across complementary stores—linking an initial centre arrival to a specific marketing campaign, and ultimately to multiple store checkouts. Answering definitively how much incremental revenue an activation generated across the tenant ecosystem remains our sector’s greatest unrealised opportunity.
If you had to choose: 20% better customer data or 20% higher footfall?
20% better customer data—assuming we possess the operational capability to act on it. Raw footfall that does not convert into tenant revenue is a vanity metric that inflates operational overhead. High-fidelity data enables us to turn existing browsers into buyers, increase visit frequency, and sustainably attract the right kind of new visitors.
If we started the shopping centre industry again tomorrow, knowing everything we know about data, AI, and consumer behaviour, would we still organise customer relationships the way we do today?
Absolutely not. We would design the customer journey as an integrated ecosystem from day one. Rather than treating leasing, marketing, parking, and loyalty as separate operational silos, we would align landlord and tenant incentives around shared success, connected infrastructure, and total transparency. We would measure asset value not by passive gate counts, but by the tangible commercial value created for both shoppers and occupiers.
More About the Author
Jurij Triller is widely recognized in the retail and shopping-center industry as one of the few experts who sees gift cards not as products, but as strategic business levers. As CEO of Smart Octopus Solutions (Slovenia, Ljubljana), he has worked with shopping centers, retail groups, and destination operators across Europe, helping them build closed-loop gift card ecosystems, loyalty platforms, and data-driven growth strategies. Within the industry, he is known not as a technology salesman, but as a strategic thinker shaping conversations about the future of retail, digital destinations, and the experience economy — and about how to turn transactions into relationships, data into decisions, and sales into long-term value.